Economists caution that improved revenue should not be mistaken for a lasting solution to South Africa's debt challenge.
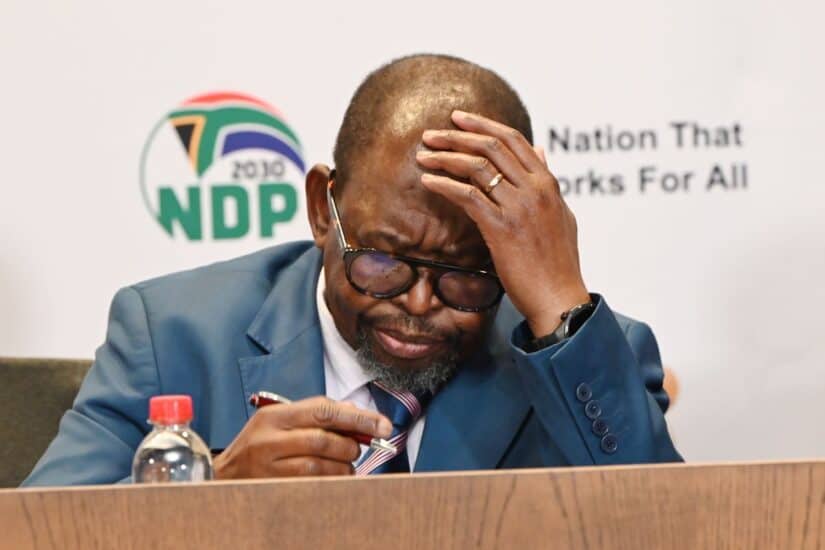
Finance minister Enoch Godongwana. Picture: Gallo Images/Frennie Shivambu

National Treasury is expected to use Wednesday’s medium-term budget policy statement (MTBPS) to reinforce its commitment to stabilising government debt, as stronger tax collections give the government some breathing room despite a weaker economic outlook.
Economists expect Finance minister Enoch Godongwana to report an improvement in South Africa’s fiscal position when he delivers the MTBPS, with the budget deficit potentially narrowing and the primary budget surplus strengthening beyond earlier projections.
However, they caution that putting government debt on a sustainable path will require more than a temporary revenue boost. Sustained spending discipline, stronger economic growth, and continued structural reforms will be critical to ensuring that the improvement in public finances lasts.
MTBPS to shine a spotlight on commitment to fiscal discipline
Investec Treasury economist Tertia Jacobs expects the Treasury to reaffirm its commitment to fiscal discipline by focusing on reducing the budget deficit, strengthening the primary surplus, and managing government debt.
“The economic outlook has weakened since the February Budget Review, as higher energy prices, tighter monetary policy, and subdued investment continue to constrain growth,” she said.
“We forecast South Africa’s GDP growth at 1.0% in 2026, below Treasury’s previous estimate of 1.6%. Inflation is also expected to be higher, projected at 4.4% compared to Treasury’s earlier forecast of 3.4%.”
Jacobs noted that despite these pressures, tax collections have been stronger than expected, providing some relief to the fiscus.
Revenue collection
Sanlam Investments economist Patrick Buthelezi expects the main budget deficit to come in below the 3.7% of gross domestic product (GDP) projected in February.
He said revenue collections could exceed the budget by R30 billion or more, even after accounting for temporary fuel levy relief that cost the government more than R17 billion in forgone revenue.
“The strong revenue performance can be attributed mostly to corporate income tax, VAT and personal income tax. These reflect buoyant terms of trade, the two-pot system, and improved efficiencies at the South African Revenue Service (Sars),” added Buthelezi.
Primary budget surplus
Chief economist at PSG Financial Services, Johann Els, expects the revenue overrun to reach R50 billion or more. He forecasts the budget deficit could narrow to about 3.5% of GDP in the current financial year, compared with the 4% projected in the February Budget.
Els also expects the primary budget surplus, the difference between government revenue and non-interest spending, to reach about 1.9% of GDP, up from the 1.4% projected in February.
A stronger primary surplus matters because it means the government is collecting enough revenue to cover spending before interest payments on existing debt. If sustained, this can help slow debt accumulation and put the debt-to-GDP ratio on a more sustainable path.
Government debt
However, economists caution that improved revenue should not be mistaken for a lasting solution to South Africa’s debt challenge.
Buthelezi said government debt, which is close to 80% of GDP, should begin declining steadily. But rebuilding the government’s financial capacity will require persistent primary surpluses, firm control of spending, and stronger economic growth.
“On the expenditure side, the Treasury has been broadly holding the line. The wage bill, one of the biggest expenditure items, does not pose an immediate threat due to a three-year wage agreement which provides near-term certainty,” he added.
“Additionally, controls on public service headcount and a voluntary early retirement programme should help contain the government wage bill.
“Importantly, the government remains committed to shifting expenditure away from consumption to infrastructure and investment, laying the foundation for higher potential growth.”
Fiscal anchor
Jacobs said the proposed fiscal anchor is expected to be a central feature of the MTBPS. Such a framework would link the government’s fiscal policy to measurable targets and greater accountability, potentially strengthening confidence in its ability to manage public finances.
However, its success will depend on whether the government can consistently deliver the primary surpluses needed to reduce debt and limit the growing cost of servicing it.
Godongwana is also expected to maintain its focus on infrastructure investment and structural reforms, particularly in rail and logistics, to improve the economy’s growth potential.
Although these measures may take time to deliver results, stronger growth would support revenue collection and make debt stabilisation more sustainable.
SA’s credit rating
Els said the combination of improved fiscal discipline and gradual structural reforms strengthens the case for sustained improvement in South Africa’s sovereign credit ratings.
Positive rating outlooks from international agencies could support further upgrades if the government maintains progress on fiscal consolidation, debt stabilisation and economic reforms.
“The better fiscal numbers help, but so does the evidence that the improvement is not only about higher commodity prices. The expected proposals around a fiscal anchor should also be positive for confidence in the medium-term fiscal outlook.
“Further ratings upgrades are likely to occur, but the question is whether we see more action after the MTBPS or whether the agencies wait for confirmation in the February 2027 Budget.
“South Africa could be back in investment-grade territory within two to three years, with at least one or two of the three major ratings agencies potentially upgrading the country back to investment grade.”
Municipalities
The mini-budget comes two weeks ahead of the Local government elections on 4 November. Absa group senior economist Miyelani Maluleke and Economist Sello Sekele argue that the minister is expected to give an update on municipal compliance.
“The National Treasury has argued that governance, financial and service delivery challenges in municipalities have become a growth and fiscal risk. Some 162 (out of 256) municipalities are assessed to be in financial distress.
“Treasury has since taken a more interventionist approach to tackling these problems. The July decision to withhold equitable share transfers to 69 municipalities is evidence that Treasury is willing to use unorthodox means to push for changes.
“We expect the Treasury to provide an update on municipal compliance. We also expect an update on the Metro Trading Service Reform, aimed at shifting to a utility model for water and electricity in some municipalities where revenues will be kept for infrastructure maintenance rather than be treated as part of general revenue.”