There are millions of ounces in old workings that suddenly look attractive at current prices.
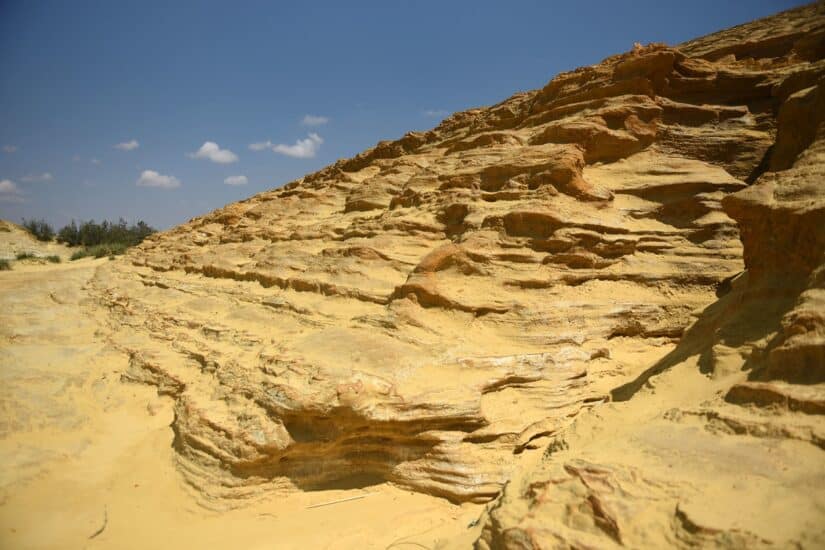
Simmer Gold Mining tailings at Slovoville in Roodepoort, 22 September 2026, which specialises in the reclamation of gold from old mining dumps. Picture: Nigel Sibanda/The Citizen


PwC’s SA Mine 2026 report holds out the tantalising possibility that South Africa cannot yet be written off as a global force in gold.
Millions of ounces remain trapped in old underground workings, in pillars, dumps and overlooked reef extensions. Some of them are kilometres underground. At current prices around $4 200 an ounce, many of these neglected ounces suddenly look attractive.
Across the globe, there were no major gold discoveries in 2023 or 2024, compared with more than 20 a year during the 1990s. Yet the world’s top 40 gold producers recorded an aggregate Ebitda (earnings before interest, tax, depreciation and amortisation) margin of 71% in 2025.
These are Nvidia-type margins that will inevitably attract investment – even in an environment perceived as hostile to mining.
“For South Africa, the opportunity is consequently not simply to find more gold. It is to convert known geology, historic infrastructure, research capability and mining expertise into new mineable ounces,” says the report.
The US Geological Survey, a federal agency, estimates SA’s gold reserves at 5 000 tonnes, or 161 million ounces. That’s more than Canada, China and Ghana, but less than Australia.
Joburg gold revival
The best evidence of this gold revival is taking place west of Johannesburg, at the centre of one of the world’s most intensively mined gold districts.
In March this year, West Wits Mining completed the first gold pour from its Qala Shallows operation, described as SA’s first new underground gold mine in more than 15 years. It is targeting steady-state production of about 70 000 ounces a year.
In February, West Wits announced a 2.2 million-ounce increase in the mineral resource of its Witwatersrand Basin Project, taking it to 7.24 million ounces at an average grade of four grams a tonne.
Roughly 1.2 million ounces of the increase came from a newly granted prospecting area extending the Kimberley Reefs at depth.
Another million ounces entered the estimate because higher gold-price assumptions allowed the company to lower its cut-off grade – the minimum gold content required to mine commercially.
Qala Shallows was able to reduce set-up costs by using previously developed underground access and nearby processing infrastructure.
Areas of opportunity
PwC identifies the most prospective opportunities across the Witwatersrand system, including the Central and West Rand in Gauteng, the Carletonville and Far West Rand districts, areas between Klerksdorp and Hartebeestfontein in North West, the Evander goldfield in Mpumalanga and areas around Welkom in the Free State.
These are previously mined areas where opportunities remain to uncover new ounces from reef extensions, remnant areas, old support pillars and deposits stranded by historic ownership structures.
Unlocking these ounces, however, requires a national “remaining gold inventory” to identify where stranded resources and existing infrastructure could support a gold revival.
New technology, new possibilities
There are plenty more ounces to be extracted from old tailings dumps that have been processed using the best technologies of their time.
Improved gold prices and better technology – such as hydraulic mining using high pressure water jets to break down and wash surface tailings – open new possibilities for retreating some of these dumps.
Pan African Resources’ Soweto Tailings Retreatment Project on the West Rand is a case in point.
Its September 2026 feasibility study identifies reserves of about 108 million tonnes at 0.28 grams a tonne, containing approximately 980 000 ounces of gold. The proposed operation is designed to produce 35 000 to 40 000 ounces a year, with estimated total production of about 561 000 ounces over roughly 15 years.
This is the type of opportunity awaiting many other previously abandoned gold sites around the country – particularly those not overrun by zama-zamas.
PwC’s analysis shows gold reserves increasing from 68 million ounces in 2023 to 77 million ounces in 2026, despite the additional three years of mining.
Estimated average remaining mine life increased from 27 to 29 years.
Higher prices, investment and improved technology are helping replace mined ounces by making more of the known deposits economically recoverable.
Strategic aspects
Progress in reviving old gold mines also depends on bringing artisanal miners under the law, something the 2025 Mineral Resources Development Bill proposes through a licensing regime for artisanal and small-scale miners.
Formalisation can create a path for legitimate community participation, but will only work if licensing is accessible, mineral flows are traceable and safety and environmental standards are enforced, says PwC.
“Otherwise, yesterday’s mine can rapidly become tomorrow’s illegal mining network,” says the report.
“SA’s next gold era will not be won by chasing depth alone, nor by waiting for another 1886 [when gold was discovered in the Witwatersrand].
“It will be won by converting what the country already knows into what it can safely and sustainably produce: mapping every remaining ounce, reopening the right ground, retreating the right tailings, formalising legitimate small-scale participation, and applying modern technology to one of the world’s greatest mineral systems.”
This article was republished from Moneyweb. Read the original here.